What is the fastest way to pay off a home loan faster?
Ever seen someone celebrate paying off their mortgage faster? That mix of envy and motivation hits hard when you’re staring down decades of payments, especially on your first home.
Suddenly all you want to do is pay off the home loan faster.
But here’s the catch: throwing every spare dollar at your mortgage can leave you financially vulnerable. Done right, you’ll accelerate repayment while maintaining flexibility for life’s curveballs.
This guide reveals proven strategies to slash your mortgage term without leaving you tight on funds. From payment frequency changes to offset accounts, you’ll discover practical methods that fit your budget.
Here at Crester Credit we provide a range of loans to help you reorganise your finances and look to the future with renewed confidence.
12 ways to reduce pay off your home loan faster
Let’s look at 12 ways to reduce the duration of your mortgage, saving on interest rate while also bringing a valuable asset into the fold. We’ll use the following scenario throughout this article.
- Mortgage: $600,000
- Mortgage term: 30 years
- Interest rate: 5%
- Interest: Calculated daily/added monthly
- Payments: Principal and interest
1. Repay your loan as if you’re on a shorter term
It’s important to find a balance between what you can afford, ensuring that you leave enough “headroom” to accommodate unforeseen circumstances. However, the most basic way to pay off your mortgage faster is to reduce its duration.
Using the above scenario:
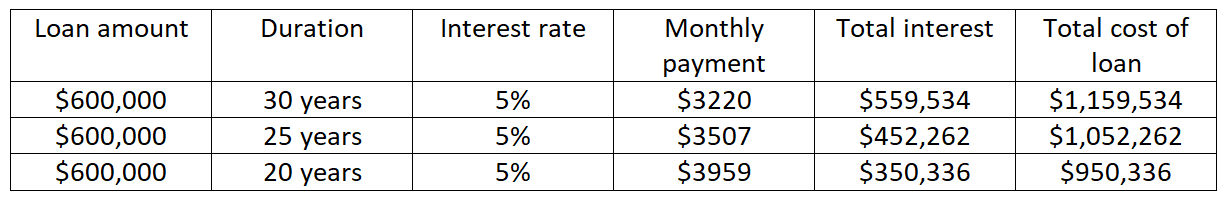
While the loan repayments will increase with a shorter duration, on the above mortgage, you would save in excess of $200,000 in interest between a 30 year mortgage and a 20 year mortgage.
2. Increase monthly repayment via overpayments
Many mortgage companies will allow you to make regular payments a bit over the required amount, which has a huge impact on the loan duration, and total interest you’ll pay. The sooner you begin to increase your regular payments, the more you’ll save in interest because of the compounding effect.
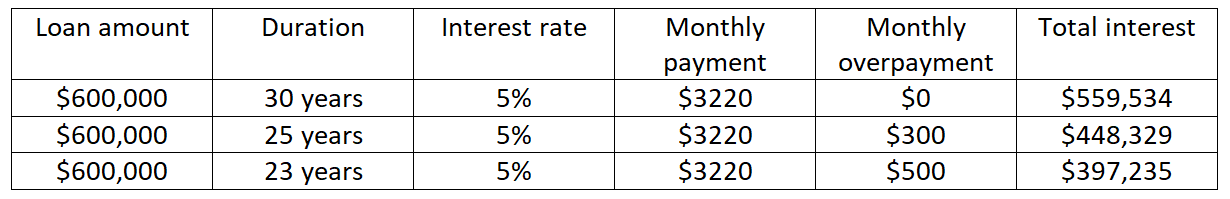
As you can see from the table above, not only are the amount of interest you pay over the duration of your mortgage but regular monthly overpayments also reduce the duration. While the above figures assume that regular monthly overpayments are made from month one, even sporadic overpayments will reduce the overall cost of your mortgage.
You don’t even need to increase your repayments over $300. Even an extra $20 can make a big difference over time. In fact, paying an extra $20 for 20 years compared to paying $40 about 10 years later will have a big difference, even if you end up paying the same amount. Based on the same loan terms above, paying an extra $20 for 20 years will save you $23,000 in interest over the loan’s term.
3. Match your income increases to your mortgage payments
When you receive a pay rise or land a higher-paying job, redirect that extra income into your mortgage repayments instead of celebrating with new purchases. This works because you’re already used to your previous income, so the increase won’t impact your lifestyle.
Getting ahead of your minimum repayment schedule also creates a safety net. If unexpected expenses arise or your financial situation changes, you’ll have the flexibility to reduce payments back to what you were originally paying.
Make this increase automatic by setting up higher payments as soon as your new salary kicks in, before you get used to the extra money in your account. Consult your mortgage adviser to ensure you won’t encounter any fees, especially if you’re on a fixed mortgage.
4. Pay mortgage and closing fees upfront, not on loan
Common fees that borrowers add to their loan include application fees, valuation costs, legal fees, and mortgage insurance premiums. For example, if you add a $2,000 mortgage insurance to a 25-year mortgage at 6% interest, you’ll end up paying about $4,300 over the loan term, more than double the original cost.
While it seems convenient to roll these costs into your mortgage when cash flow is tight, the long-term impact is significant so think twice before doing it. That extra $2,000+ you’ll pay upfront can help you repay your mortgage faster.
5. Make lump sum overpayments
Received an inheritance, tax refund, or sold some shares? Did you recently get a pay rise as a result of a promotion? Consider directing these extra funds toward your mortgage rather than spending them elsewhere.
Making a lump sum repayment dramatically reduces your loan principal and helps pay off your loan faster. Rules vary significantly between mortgage types, so check with your mortgage broker before making extra payments.
In general, fixed rate home loans have restrictions. Some allow extra repayments without being charged, up to 5% of your total loan balance annually. With others, you may get charged an early repayment fee, and not all of the repayment might go towards paying the capital. The fees can be substantial, potentially negating the benefits of your extra payment.
Floating-rate loans often offer more flexibility, allowing unlimited extra repayments without additional costs. This makes them ideal if you regularly receive bonuses or other irregular income.
In the following example, we will assume that an overpayment is made in addition to the first monthly repayment.
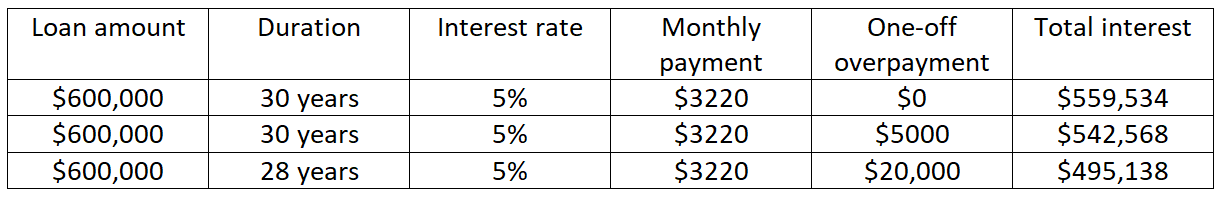
You receive the maximum benefit from a lump sum payment the earlier it is used to pay off part of your mortgage capital. This is because you will pay less interest, and more of your monthly payments will go towards the repayment of capital. Use a mortgage calculator or get professional advice from a licensed broker to see how this approach can help you pay the mortgage faster and pay less interest.
6. Pay your loan faster with increased monthly payment and lump sum overpayment
While the stand-alone benefits of an increase your regular repayments and a one-off lump sum overpayment are well demonstrated above, combining them can have a huge impact. It’s one of the fastest ways to pay your loan early. Even the monthly overpayments in the table below equate to $3600 and $6000 per year, which is no small amount.
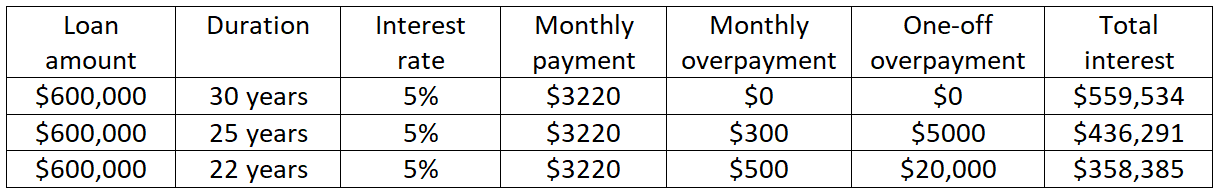
Introducing a $20,000 one-off overpayment and making an additional regular repayment a month equates to a significant decrease in the interest you’ll pay over the life of the loan.
7. Change the loan structure to fortnightly repayments
Instead of making 12 monthly payments annually, switch to fortnightly payments and you’ll make 26 payments per year, equivalent to 13 monthly payments.
The strategy is straightforward: take your monthly repayment amount, divide it by two, and pay that amount fortnightly. Call your bank to make changes to your repayments, most lenders can accommodate this request easily.
Here’s a basic calculation using the same scenario above:
$600,000 loan at 5% for 30 years:
- Monthly payment: approximately $3,221
- With fortnightly payments of $1,610.50 (half the monthly), you make 26 payments = 13 months worth annually
The two extra fortnightly payments could reduce your loan term by approximately 4 years and lessen the amount of interest you’ll pay by about $80,000-$90,000.
Since your repayments are spread throughout the year, you’re less likely to notice the extra funds taken.
8. Split your mortgage to make a portion of your home loan floating
Consider splitting your total mortgage amount between fixed rate mortgage and floating rate mortgage to get the best of both worlds, payment certainty and flexibility for extra repayments. This doesn’t mean you have two loans, it’s just one loan and your payments will be split between the loan types.
Fixed rates provide predictable repayments, however it usually restricts extra repayments, often charging penalties that can negate your interest savings.
Floating rates fluctuate with the Reserve Bank’s Official Cash Rate changes, making them less predictable. Its advantage is the flexibility, you can make unlimited extra repayments without penalties.
An example split structure is putting 70% of your loan on fixed rate for payment certainty while keeping the 30% floating for extra repayments. When you receive bonuses, tax refunds, or other unexpected money, you can direct these towards your home loan floating segment without worrying about early repayment charges, so you can pay off your loan faster and the less interest you’ll pay. Seek financial advice from a licensed mortgage broker first before doing this, so they can give you options based on your situation and goals.
9. Pay your first payment on the start of your loan
Interest begins accruing on your full loan amount as soon as you settle the mortgage agreement. By making an immediate payment, you reduce the principal that interest is calculated on, creating instant savings that compounds over the life of your loan.
The amount you pay doesn’t need to be large, even the regular monthly payment makes a huge difference. That one extra payment goes a long way towards paying off your home loan early.
Here’s what an immediate payment looks like on a $600K loan
- You settle on January 1st and immediately make a payment (let’s say $3,200)
- Now you’re only paying interest on $596,800 instead of $600K
That $3,200 reduction in principal means less interest accumulating every single day for the life of your loan. It makes a huge difference in the long run.
10. Use your savings account for an offset mortgage
What is an offset mortgage? An offset mortgage links your everyday savings account to your home loan. It deducts your savings balance from your mortgage when calculating interest.
If you had a mortgage of $600,000, with $25,000 in your savings account, that amount would be offset, meaning that you only pay interest on a balance of $575,000.
In the following example we will assume that savings remain in the account for the duration of the mortgage, earning 1% per annum.
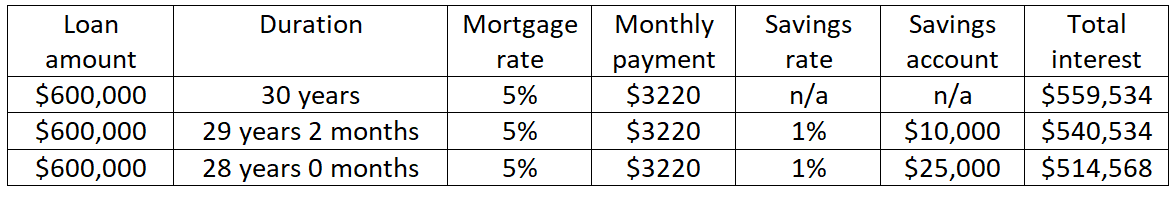
You can keep your repayments the same, but more of it goes toward principal, helping you pay the loan off faster.
Mortgage rates typically exceed savings rates, so you save more by offsetting than earning interest on saving. Obviously, the mortgage interest savings would be less if you were to spend any of your savings.
Tax advantages add further appeal. You won’t pay tax on “interest earned” since your savings reduced the mortgage interest instead of generating taxable income.
Offset mortgages give you complete access to your savings, while allowing unlimited overpayments without penalties. . This flexibility makes it ideal for borrowers wanting to pay their loan faster and pay less in interest, with the added benefit of having a savings account. Rates and fees are subject to change, so please ask your broker before signing up for an offset mortgage.
11. Combine offset mortgage with regular top-ups to your savings
The potential savings of using an offset account are even greater if even small monthly contributions to your savings account.
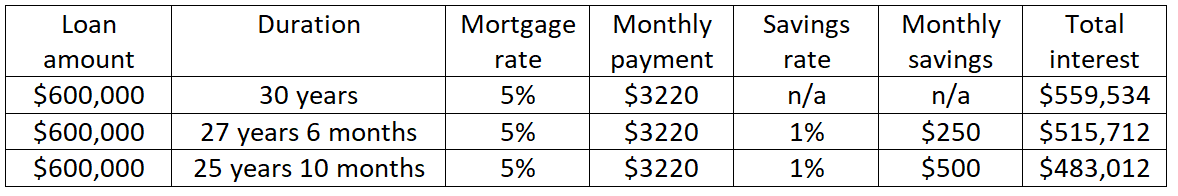
You can also reduce the loan even further by using the saved up money to make a lump sum payment to the mortgage.
12. Use business cashflow to allow you to increase offset mortgage savings
There is the potential to get a little more innovative when it comes to offset mortgages. For example, if your company has extra cash flow, consider putting it towards your savings to offset your mortgage balance. There may be tax and legal implications to consider before doing this, so ask your financial advisor if your home loan could accept this payment.
For now, let us assume that for 25 days of each month your company has a positive cash balance. At the end of this period, invoices/employees are paid, and then income is received, reverting to a positive cash balance. In the examples below we will use $30,000 and $60,000 cash flow availability. We need to calculate the average offset balance over the full month. The calculation is as follows:-
- Average month: 365/12 = 30.4 days
Average balance: 25/30.4 x Available funds - Example 1: (25/30.4) x $30,000 = $24,671
Example 2: (25/30.4) x $60,000 = $49,342
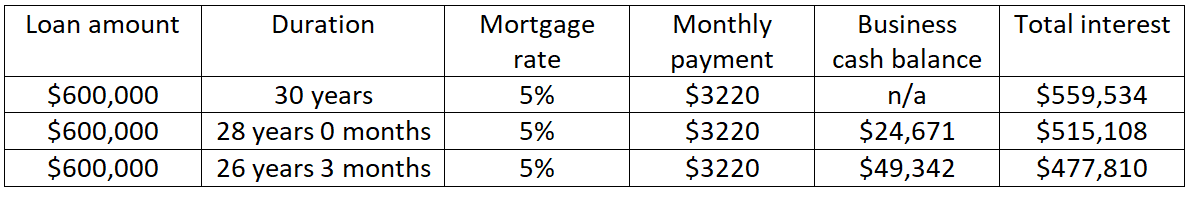
The hypothetical opportunity to use business cash flow to offset against a personal mortgage has the ability to save significant interest as shown above. This concept could also be extended to business mortgages where the funds would still be retained within the company – this may be less complicated!
The opportunity to use business cash flow to offset against a personal mortgage can help you pay the loan sooner than you think. This strategy could also be extended to business mortgages where the funds would still be retained within the company, but this might be more complicated so ask your financial advisor.
Increase your mortgage repayments strategically
Whether increasing your monthly repayments, introducing one-off lump sum repayments or offsetting savings account/cash flow balances against your outstanding mortgage, the faster you pay, the more you’ll save in interest during your mortgage. Obviously, all of these options need to be considered in light of your current and future financial situation. While offset mortgages are slightly different, once you have made a payment to a traditional mortgage you cannot get it back, so that’s something to consider as well.
The concept of using business cash flow is an interesting idea but you would need to consider company and personal taxes, as well as company regulations.

by Ash Horton
February 24, 2022
Ash is a professional content writer with extensive experience in business development in the financial services. Ash has founded businesses from the age of 19, including franchising ventures, and working alongside some of the largest retailers in the world.